Taxation
Written by: Umar Bostan
Updated on30 October 2026
Taxation
Taxes can be classified as progressive, proportional or regressive, depending on how the tax burden changes as income rises.
Progressive, Proportional and Regressive Taxes
Progressive Taxes
A progressive tax is one where, as income rises, a larger percentage of income is paid in tax. The UK income tax system is an example, as higher levels of taxable income face higher marginal tax rates.
For example:
Up to £12,500 → 0%
£12,501–£50,000 → 20%
£50,001–£150,000 → 40%
Over £150,000 → 45%
Moving into a higher tax band does not mean that all income is taxed at the higher rate. Only the income within that band faces the higher rate — this is known as the marginal tax rate.
For example, someone earning £60,000 pays no tax on the first £12,500, 20% on the next £37,499 and 40% on the remaining £10,001.
Progressive taxation can reduce income inequality. Higher-income households pay a greater proportion of their income in tax → government revenue can be redistributed towards lower-income households or public services → income inequality may fall.
Proportional Taxes
A proportional tax charges the same percentage of income regardless of income level.
For example, with a 10% proportional tax:
£10,000 income → £1,000 tax
£100,000 income → £10,000 tax
Both individuals pay 10% of their income, even though the absolute amount of tax paid is different.
Regressive Taxes
A regressive tax is one where, as income rises, a smaller percentage of income is paid in tax.
Indirect taxes such as VAT can be regressive because lower income households tend to spend a larger proportion of their income on consumption.
For example In the UK, the poorest 10% of households pay around 27% of their disposable income in indirect taxes like VAT, compared to just 14% paid by the richest 10% (ONS).
Regressive taxation can therefore worsen income inequality and partly offset the redistributive effect of progressive direct taxes.
Economic Effects of Changes in Tax Rates
Incentives to Work
Higher income tax rates reduce the financial reward from earning additional income.
Higher income tax → workers keep less of each additional £ earned → opportunity cost of leisure falls → incentive to work overtime, seek employment or increase hours may fall → labour supply and productive activity may decrease.
However, the effect depends on how responsive workers are to changes in their post-tax income. Some workers may instead work more hours to maintain their desired level of disposable income.
Tax Revenue and the Laffer Curve
The Laffer Curve shows the theoretical relationship between the tax rate and government tax revenue.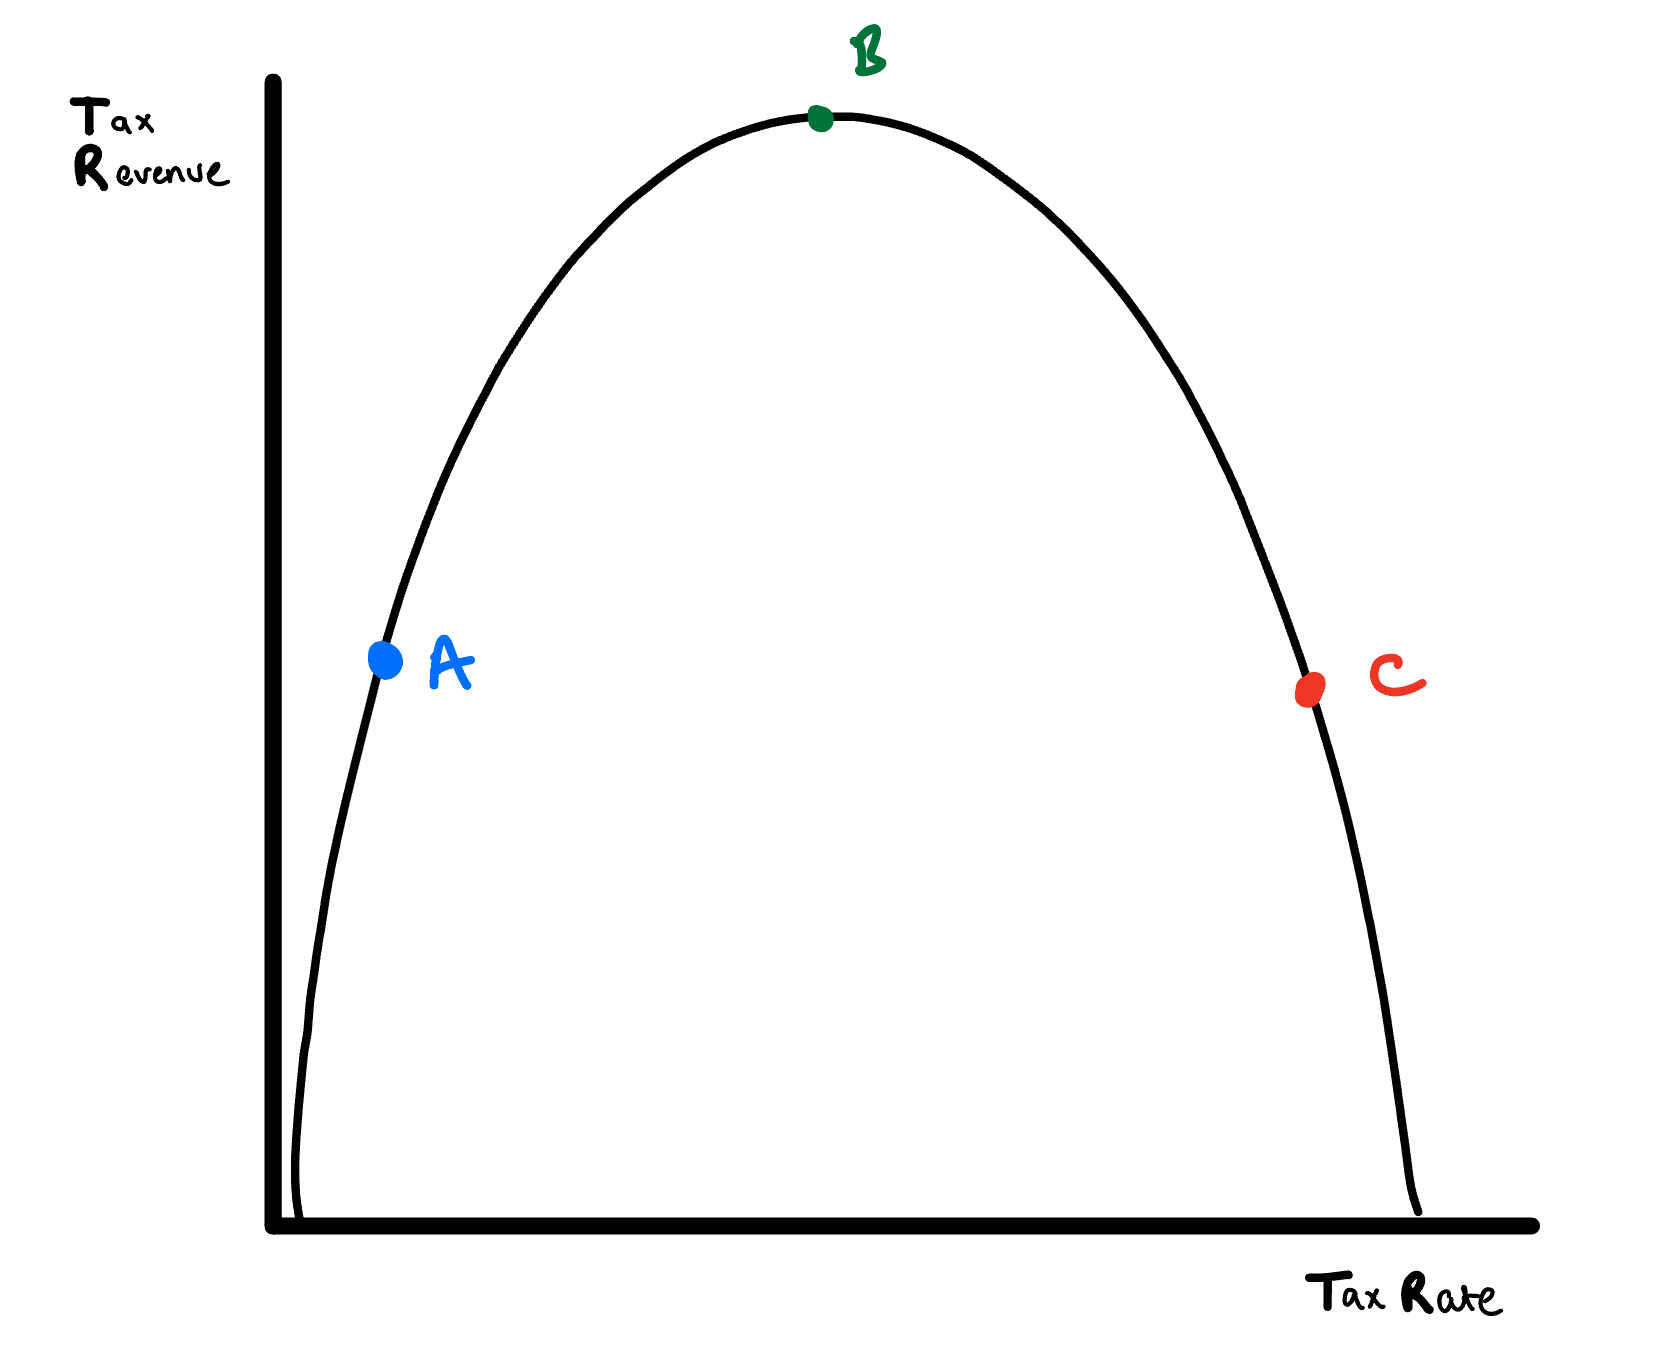
Initially:
Higher tax rates → more tax collected per unit of taxable income → government tax revenue rises (e.g raising tax rate from point A to point B leads to much higher tax revenue )
However, beyond a certain tax rate:
Very high tax rates (e.g from point B to point C )→ weaker incentives to work and earn taxable income + greater incentive for tax avoidance → taxable economic activity falls → government tax revenue may decrease.
Therefore, increasing tax rates does not necessarily increase tax revenue. The effect depends on the existing tax rate and how strongly households and firms change their behaviour.
For some context the UK increased its Corporation Tax in19% to 25% in 2023 , this was estimated to generate roughly £18 billion per year, demonstrating that the UK is not at the optimal point of the laffer curve yet (not at point B) .
Income Distribution
Progressive taxation can redistribute income from higher-income households towards lower-income households.
Higher taxes on high incomes → greater government revenue → more funding for benefits and public services → disposable income differences narrow → income inequality may fall.
Real Output and Employment
Higher taxation represents a greater withdrawal from the circular flow of income.
Higher taxes → lower household disposable income and/or lower firm profits → consumption and investment fall → AD decreases → real output falls → firms require fewer workers → unemployment may increase.
Conversely, lower taxation → higher disposable income and profits → consumption and investment increase → AD rises → real output and employment may increase.
Average Price Level
Higher indirect taxes increase firms’ costs and the prices consumers pay for goods and services.
Higher indirect taxes → higher costs of production → SRAS shifts left → average price level rises → cost-push inflation.
Indirect taxes may also reduce real disposable income → workers demand higher wages to maintain purchasing power → firms’ labour costs rise → prices increase further → potential wage-price spiral.
Trade Balance
Higher taxation can reduce household disposable income and therefore reduce spending on both domestic and imported goods.
Higher taxes → lower disposable income → consumption falls → demand for imports falls → import expenditure decreases → trade balance (X − M) may improve.
The size of the improvement depends on how much consumers reduce their spending and how much of that spending would have gone towards imports.
Foreign Direct Investment
Corporation tax affects the returns firms receive from investing in a country.
Higher corporation tax → lower post-tax profits → country becomes relatively less attractive to multinational firms → inward FDI may decrease.
However, the effect depends on relative corporation tax rates between countries, alongside other factors such as infrastructure, labour skills and access to markets e.g despite UK increasing its corp tax rate to 25% it is still much lower than other G7 economies such as Germany at 30% .
Active recall
Revise with flashcards
Teacher Information
More Revision Notes you might like
Specification 4.5.2
Past paper questions on this topic
12 matched questions to practise alongside these notes.
- A-level Paper 2, June 2025, Q6(a) · 5 marks
With reference to Figure 1, explain the distinction between direct and indirect taxation.
- A-level Paper 2, June 2024, Q6(a) · 5 marks
With reference to Figure 4 and your own knowledge, explain the distinction between a progressive and a regressive tax.
- A-level Paper 2, June 2024, Q6(b) · 8 marks
With reference to Figure 4 and Extract A, examine the likely impact of the ‘freeze in income tax thresholds’ (Extract A line 1) on aggregate demand.
- A-level Paper 3, June 2023, Q1(d) · 25 marks
Evaluate microeconomic and macroeconomic policies that could be used to reduce inequality in the UK.
- A-level Paper 3, June 2023, Q1(e) · 25 marks
Evaluate the likely microeconomic and macroeconomic effects of tax cuts in the UK.