Public Sector Finances
Written by: Umar Bostan
Updated on30 October 2026
Automatic Stabilisers and Discretionary Fiscal Policy
Automatic Stabilisers
Automatic stabilisers are changes in government spending and tax revenue that occur automatically as the economy moves through the economic cycle. They do not require the government to introduce a new policy.
During a recession:
Increasing unemployment → welfare spending increases (govt did not plan to increase spending on welfare but due to downturn in economic cycle more is spent on welfare)
For example after the 2008 financial crisis welfare benefit expenditure increased by £13.5 billion between 2007/08 and 2009/10.
During an economic boom:
Higher incomes → individuals pushed into higher tax brackets → tax revenues rise → less unemployment → welfare spending decreases
For example individuals pushed up from the 40% tax bracket into the 45% tax bracket
Automatic stabilisers therefore help reduce fluctuations in aggregate demand across the economic cycle.
Discretionary Fiscal Policy
Discretionary fiscal policy occurs when the government deliberately changes government spending or taxation to influence the economy.
For example in 2023 when the UK govt increased corporation tax rates form 19% to 25% .
Alternatively, fiscal austerity involves reducing government spending and/or increasing taxation to improve the government’s fiscal position.
Fiscal Deficit and National Debt
Fiscal Deficit
A fiscal deficit occurs when government spending exceeds government tax revenue in a given year.
Government spending > government revenue → fiscal deficit.
For example in 24/25 the fiscal deficit reached over £120bn+ (4.3% of GDP)
National Debt
The national debt is the accumulation of previous government borrowing and fiscal deficits.
Fiscal deficit → government needs to borrow → national debt increases.
For example the UK national debt stands at roughly £2.9 trillion (around 94% of GDP)
The key distinction is that the fiscal deficit is the amount borrowed in a year, whereas national debt is the total accumulated amount owed from previous borrowing.
Structural and Cyclical Deficits
Cyclical Deficit
A cyclical deficit occurs because of a downturn in the economic cycle, usually during a recession.
Recession → incomes and profits fall → tax revenue falls → unemployment rises → welfare spending increases → fiscal deficit increases.
Cyclical deficits should reduce naturally as the economy recovers because automatic stabilisers begin working in the opposite direction.
For example Germany usually experiences cyclical structural deficits . This means in a boom they will usually experience a budget surplus whereas in a recession may fall into a budget deficit . Germany helps illustrates how entering a downturn with a surplus provides more room to respond. Surpluses in stronger years help reduce debt and create capacity to borrow more during recessions, supporting spending and employment. This can make recessions shallower and shorter due to increased potential fiscal stimuli / fiscal headroom.
Comparison: In 2019, Germany had a 1.3% of GDP surplus, while the UK had a 2.5% deficit.
Structural Deficit
A structural deficit is the fiscal deficit that remains even when the economy is operating at or around full employment.
Unlike a cyclical deficit, it is not simply caused by a temporary economic downturn. It suggests there is an underlying imbalance between government spending and government revenue.
Structural deficits could result from:
Persistently high government expenditure
Low tax revenues
Tax avoidance
For example the UK illustrates a persistent structural deficit: borrowing continues during economic expansions as well as recessions, meaning it adds to debt across the business cycle. This means even when the UK Economy is at its best it still needs to borrow to finance its govt spending , representing the severe underlying structural issues within the UK.
UK statistic: Its last budget surplus was in 2000/01, with deficits every financial year since through 2024/25. This has lead to national debt being driven up up from 35% of GDP in 2000 to nearly 100% of GDP in 2024. House of Commons Library
Factors Influencing the Size of Fiscal Deficits
Demographics and Social Factors
Changes in the population can affect government expenditure and therefore the fiscal deficit.
For example:
Ageing population → greater demand for pensions, healthcare and social care → higher government expenditure → potentially larger fiscal deficit.
For example over 19% of the UK population is currently aged 65 and over .
The level of development and expectations of state provision can also affect how much governments are expected to spend.
Unforeseen Events
Unexpected events can require large increases in government expenditure.
For example, financial crises, wars or other major shocks may require government intervention → government spending increases → fiscal deficit increases.
Factors Influencing the Size of National Debt
Size of Fiscal Deficits
National debt is the accumulation of previous fiscal deficits.
Persistent fiscal deficits → repeated government borrowing → national debt increases.
If the government runs a budget surplus, it could use some of the additional revenue to repay existing debt.
Economic Growth
The sustainability of national debt is often considered relative to the size of the economy using the debt-to-GDP ratio.
If nominal GDP grows faster than government debt → debt-to-GDP ratio falls → debt becomes smaller relative to the economy.
Therefore, a country can continue running fiscal deficits while its debt-to-GDP ratio falls, provided GDP is growing sufficiently quickly relative to debt.
For example UK national debt is around £3tn (94% of GDP)
Government Policy
Government taxation and spending decisions directly affect fiscal deficits and therefore national debt.
For example:
Cut corporation tax → government tax revenue may fall → fiscal deficit increases → additional borrowing required → national debt increases.
Discretionary government policy can therefore either reinforce or offset the effects of automatic stabilisers.
Unforeseen Events and Debt Interest
Unexpected events can require significant government borrowing, increasing national debt.
Higher debt interest payments can also worsen the government’s fiscal position → more revenue used to service existing debt → potentially greater need for borrowing.
Significance of Fiscal Deficits and National Debt
The consequences of government borrowing depend on the size of the debt, debt relative to GDP, interest rates and what the borrowed money is used for.
Interest Rates and Crowding Out
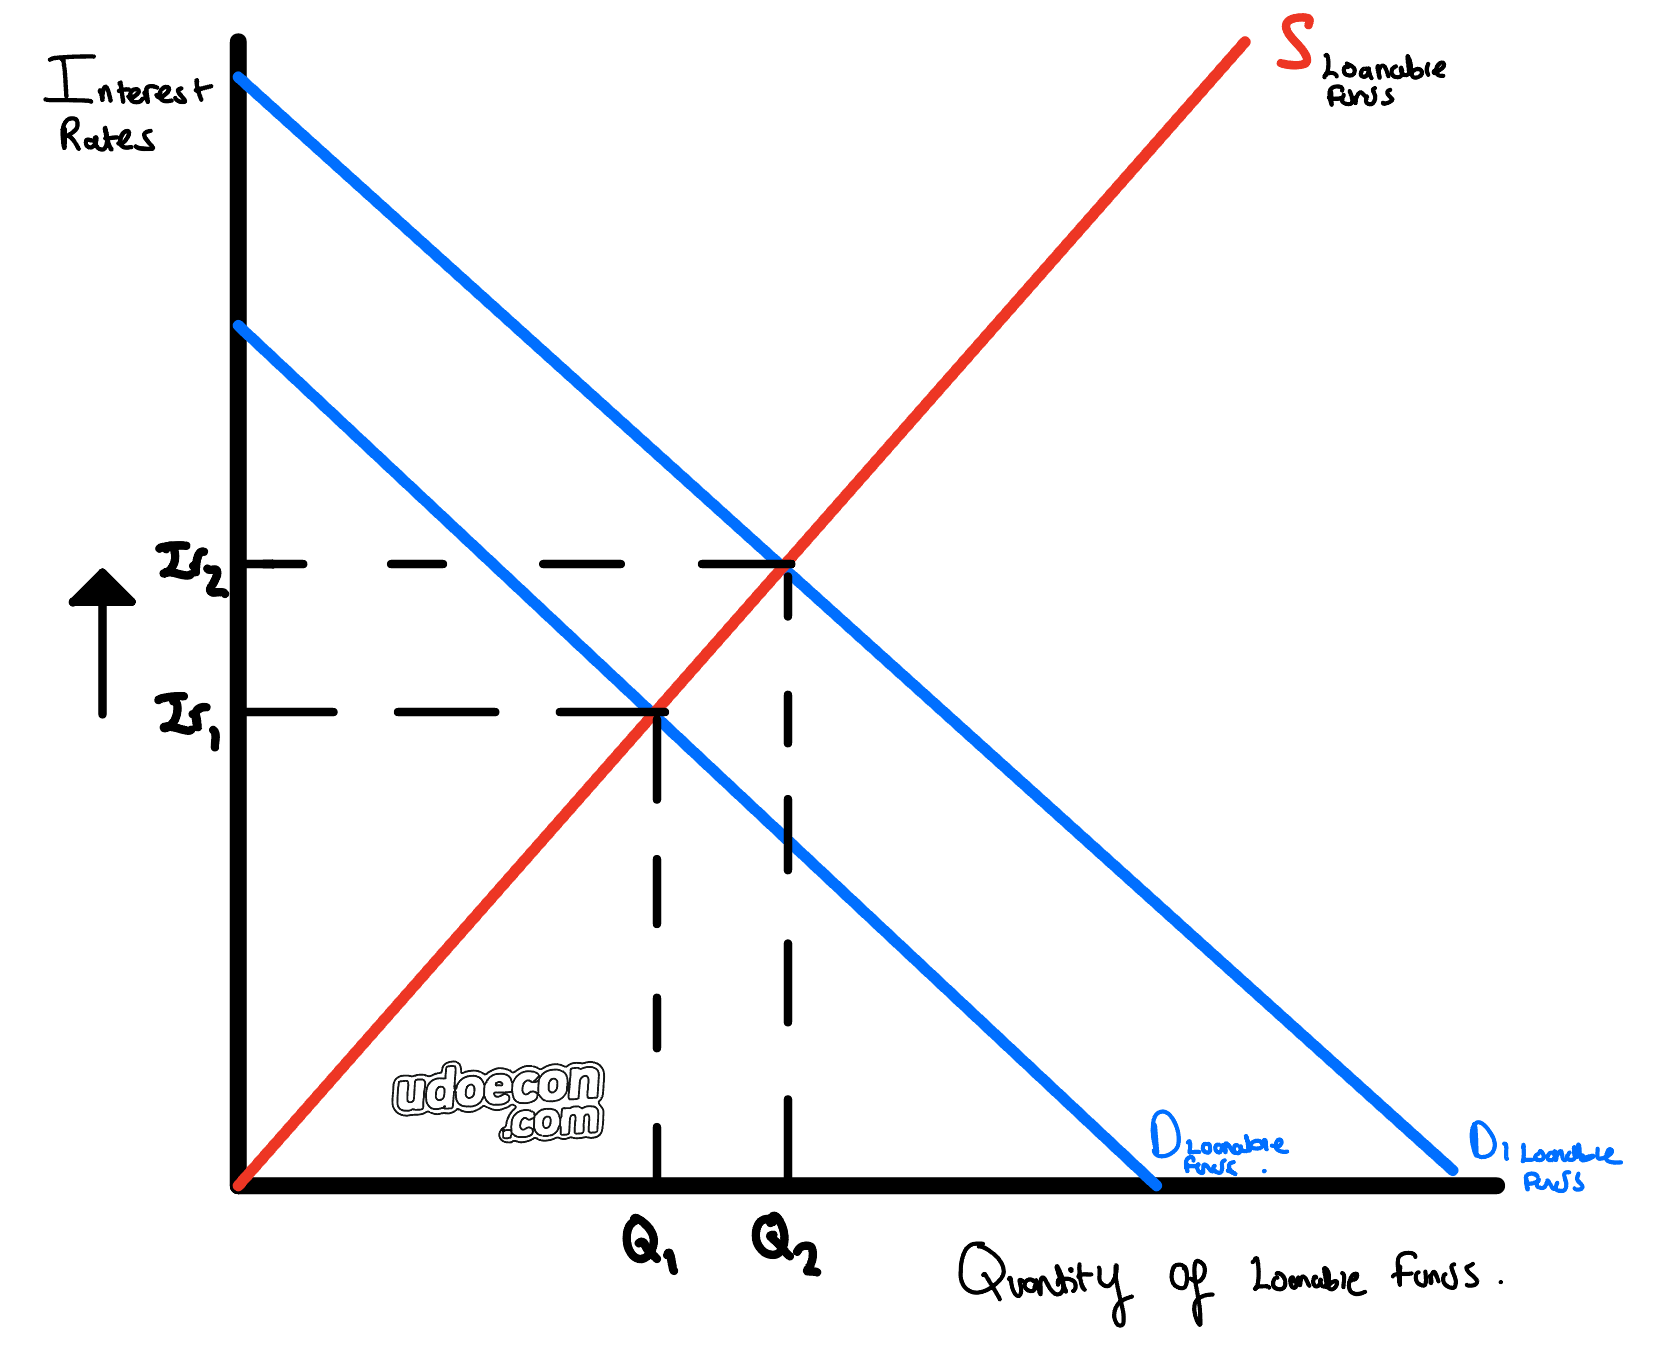
High government borrowing can increase demand for loanable funds.
Government borrowing increases → demand for loanable funds increases → interest rates rise → cost of borrowing for private firms increases → private investment falls → crowding out.
This could reduce private-sector capital investment and limit long-run economic growth.
However, the extent of crowding out depends on economic conditions. During a recession, private-sector demand for funds may already be weak, reducing the upward pressure on interest rates.
Debt Servicing
Governments must pay interest on their existing national debt.
National debt increases → debt interest payments increase → larger proportion of government revenue spent servicing debt → less available for healthcare, education and infrastructure.
There is therefore an opportunity cost to servicing government debt.
For example UK net debt interest spending consumes around £111 billion annually (around 8% of total public spending) meaning the government spends as much servicing its debt as it does on the entire national education budget.
Intergenerational Equity
Government borrowing today may create costs for future taxpayers.
Higher borrowing today → larger national debt → future governments may need higher tax revenues to service or repay debt → burden may be transferred to future generations.
This creates an issue of intergenerational equity, particularly if borrowing finances current consumption rather than investment that also benefits future generations.
Inflation
Inflation reduces the real value of nominal government debt.
Higher inflation → money loses purchasing power → existing fixed nominal debt becomes worth less in real terms → real burden of government debt falls.
However, high inflation also reduces household purchasing power and can create wider economic costs.
Credit Ratings
Credit rating agencies assess the perceived creditworthiness of governments.
Lower perceived creditworthiness → investors demand higher interest rates to compensate for greater perceived risk → government borrowing becomes more expensive → debt servicing costs increase.
Countries with stronger credit ratings can generally borrow at lower interest rates.
Foreign Direct Investment
External debt may require repayment in foreign currency.
Higher external debt → greater demand for foreign currency to service debt → governments may seek to attract FDI → foreign currency enters the economy → helps facilitate foreign-currency repayments.
However, attracting FDI can involve greater foreign ownership of domestic assets.
Active recall
Revise with flashcards
Teacher Information
More Revision Notes you might like
Specification 4.5.3
Past paper questions on this topic
15 matched questions to practise alongside these notes.
- A-level Paper 2, June 2025, Q3(b)(ii) · 2 marks
Explain one likely disadvantage of a decline in GDP on government.
- A-level Paper 2, June 2025, Q6(c) · 10 marks
With reference to the information provided and your own knowledge, assess the likely macroeconomic effects of the German government’s budget deficit.
- A-level Paper 2, June 2024, Q6(c) · 10 marks
Assess whether a fiscal deficit and national debt should be a cause for concern for the UK government.
- A-level Paper 2, June 2023, Q5(a) · 2 marks
Calculate the US national debt in 2021 as a percentage of GDP.
- A-level Paper 2, June 2023, Q5(b) · 2 marks
Explain the relationship between a fiscal deficit and the national debt.